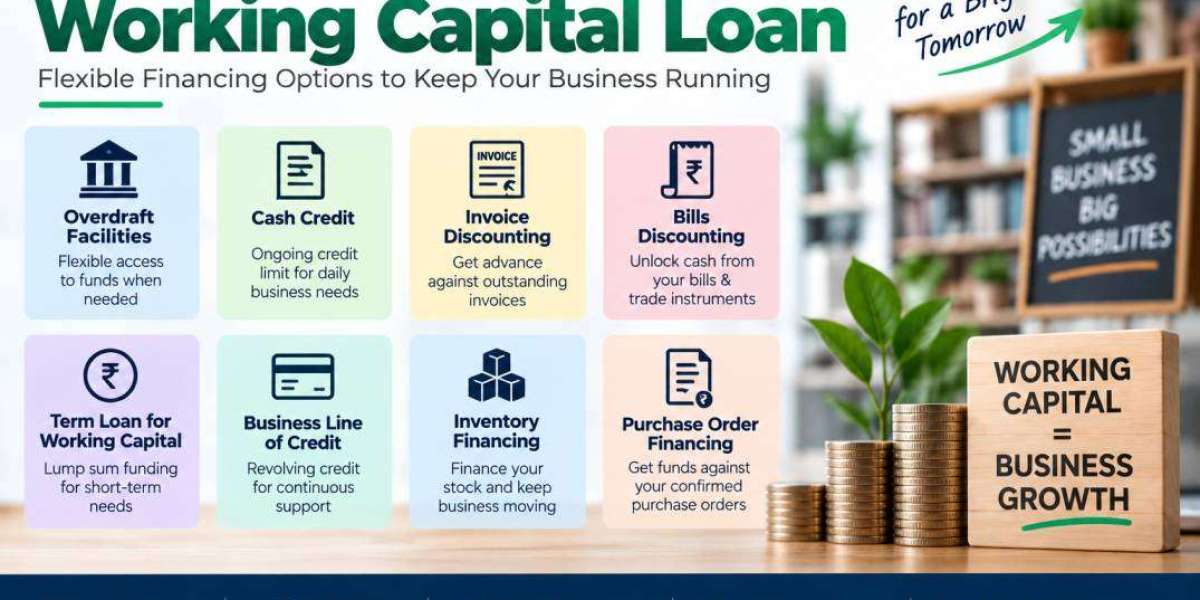

Managing cash flow is one of the most important responsibilities for any business. Even profitable businesses can experience temporary financial shortages when customer payments are delayed, inventory requirements increase, or operating expenses rise unexpectedly. A working capital loan can help businesses manage these short-term financial requirements while keeping daily operations running smoothly.
Different types of working capital loans are designed for different business situations. Understanding these financing options can help business owners choose a suitable solution based on their cash flow, business requirements, and repayment capacity.
What Is a Working Capital Loan?
A working capital loan is financing used primarily to meet the short-term operational requirements of a business. It can help cover expenses such as purchasing inventory, paying suppliers, managing salaries, paying utility bills, and handling other routine business costs.
Unlike financing intended specifically for long-term assets such as property or heavy machinery, working capital financing generally focuses on maintaining the day-to-day financial health of a business.
Why Do Businesses Need Working Capital Financing?
Businesses rarely receive all customer payments at the same time. There can be a gap between purchasing stock, delivering products or services, issuing invoices, and receiving payments. During this period, businesses still need to pay employees, suppliers, rent, and other expenses.
A working capital loan can help bridge this cash flow gap. It can also provide additional liquidity when businesses experience seasonal demand, accept large orders, expand operations, or face unexpected operating expenses.
Different Types of Working Capital Loans
1. Working Capital Term Loan
A working capital term loan provides a predetermined amount of money that the business repays through scheduled installations over an agreed period.
This type of financing can be suitable when a business has a specific short-term funding requirement and wants a structured repayment schedule. The funds may be used for inventory purchases, supplier payments, payroll, marketing, and other operational expenses.
2. Cash Credit
Cash credit is a flexible financing facility that allows eligible businesses to borrow funds up to an approved limit. Businesses can generally withdraw funds according to their immediate requirements.
It can be useful for companies with regular but fluctuating working capital needs. Interest is typically charged based on the amount utilized, subject to the terms of the facility.
3. Overdraft Facility
A business overdraft allows a company to withdraw funds beyond the available balance in its account, up to an approved limit.
An overdraft can help businesses manage short-term cash shortages, particularly when customer payments are delayed. Since the facility can be used when required, it can provide flexibility for managing temporary liquidity requirements.
4. Invoice Financing
Invoice financing allows businesses to access funds against eligible unpaid invoices. Instead of waiting until customers complete their payment cycles, a business can obtain financing based on outstanding receivables.
This can be particularly valuable for businesses that regularly sell products or services on credit and have a long receivables cycle.
5. Bill Discounting
Bill discounting is another short-term financing option where businesses can receive funds date against eligible bills before their maturity.
The financing provider pays the business an amount after applicable charges or discounts. When the bill reaches maturity, the payment is settled according to the agreed arrangement.
6. Trade Credit
Trade credit allows businesses to purchase goods or services from suppliers and make payment after an agreed credit period.
Although trade credit is different from a traditional working capital loan, it can be an important part of working capital management. It enables businesses to maintain inventory and operations without making immediate payment to suppliers.
7. Letter of Credit
A letter of credit is a banking facility commonly used to support trade transactions. It provides assurance to the seller that payment will be made subject to the terms and conditions specified in the letter of credit.
Businesses involved in domestic or international trade may use this facility to improve transaction confidence and manage payment arrangements.
8. Bank Guarantee
A bank guarantee is a commitment provided by a bank on behalf of a business to meet certain financial or contractual obligations if the business fails to do so according to the agreed terms.
It can support business contracts, tenders, projects, and other commercial transactions without requiring the business to immediately block the entire amount of its own funds.
Benefits of a Working Capital Loan
A working capital loan can provide businesses with additional liquidity when internal cash resources are insufficient. Some key benefits include:
Better management of short-term cash flow gaps
Timely payment of suppliers and employees
Support for inventory purchases
Ability to handle seasonal business demand
Improved capacity to fulfill large customer orders
Greater flexibility in managing operating expenses
Support for business expansion and growth opportunities
The actual benefits depend on the type of financing, lender terms, business circumstances, and repayment capacity.
How to Select the Right Working Capital Loan
Choosing the appropriate financing option requires careful evaluation. Businesses should first identify why they need additional funds and how long the requirement is expected to continue.
For a fixed funding requirement, a term loan may be appropriate. Businesses with fluctuating cash requirements may consider cash credit or an overdraft. Companies with significant unpaid invoices may find invoice financing or bill discounting more relevant.
Business owners should also compare interest rates, processing fees, repayment terms, collateral requirements, eligibility criteria, and other applicable charges before selecting a facility.
Working Capital Loan and Business Growth
Adequate working capital can help businesses operate efficiently and respond to market opportunities. When a company has sufficient liquidity, it can purchase inventory on time, pay suppliers, manage expenses, and fulfill customer orders without unnecessary interruptions.
A working capital loan can therefore serve as an important financial tool for businesses that experience temporary cash flow gaps. However, borrowing should be planned carefully so that repayment obligations remain manageable.
Conclusion
Understanding the different types of working capital loans can help business owners make better financing decisions. Term loans, cash credit, overdrafts, invoice financing, bill discounting, trade credit, letters of credit, and bank guarantees serve different business requirements.
The right working capital loan depends on the company's cash flow pattern, funding purpose, repayment capacity, and overall financial position. By comparing available options and selecting financing that matches their needs, businesses can manage liquidity more effectively and create a stronger foundation for sustainable growth.