
Micro, Small, and Medium Enterprises (MSMEs) play an important role in economic development, employment generation, and industrial growth. However, many MSMEs face cash flow challenges because customers often take several weeks or months to pay for goods and services supplied on credit. These delayed payments can affect inventory purchases, supplier payments, employee salaries, and daily business operations.
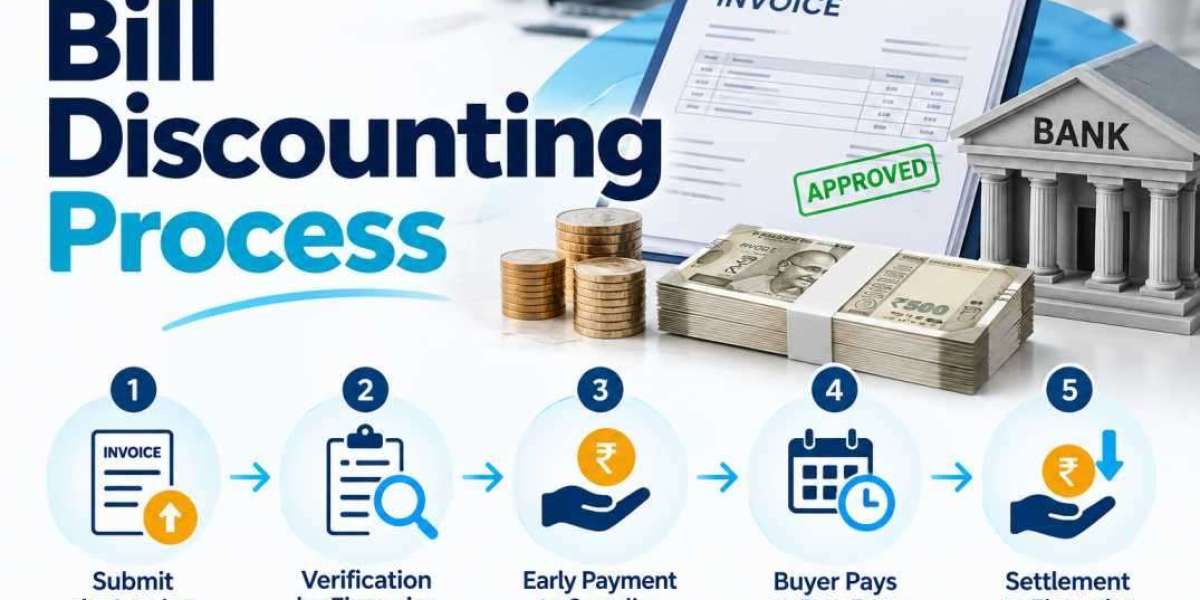
The bill discounting process offers MSMEs a potential solution by helping them access funds against eligible unpaid bills or invoices before their maturity dates. Instead of waiting for customers to complete their payment cycles, businesses can obtain financing to meet immediate working capital requirements.
Understanding each step can help MSMEs evaluate their options, prepare the necessary documents, and make informed financing decisions.
What Is Bill Discounting for MSMEs?
Bill discounting is a short-term financing arrangement in which a business receives an advance against an eligible bill or invoice from a bank or financing provider. The provider deducts applicable discount charges and fees before releasing the funds.
For example, an MSME supplies goods worth ₹3,00,000 to a buyer who agrees to pay after 60 days. If the invoice qualifies for financing, the supplier may apply for bill discounting to access a portion of the amount before the due date.
The actual advance depends on the provider's assessment, financing terms, invoice eligibility, and applicable charges. The business should also understand its obligations if the buyer delays payment or defaults.
Step-by-Step Bill Discounting Process for MSMEs
Step 1: Identify Outstanding Bills or Invoices
The first step is to review outstanding customer invoices and identify those that may qualify for financing. These invoices should relate to genuine business transactions and contain accurate information about the goods or services supplied.
MSMEs should check the invoice value, payment terms, maturity date, buyer details, and any contractual conditions. Properly maintained sales and receivables records can make the application process more efficient.
Step 2: Verify Buyer Acceptance and Payment Terms
The financing provider may require confirmation that the buyer acknowledges the payment obligation. Depending on the arrangement, this may involve an accepted bill of exchange, verified invoice, purchase order, delivery confirmation, or other supporting evidence.
Clear documentation helps establish the legitimacy of the transaction and reduces the possibility of disputes during verification.
Step 3: Choose a Suitable Financing Provider
MSMEs can explore eligible banks, financial institutions, and digital financing platforms that offer invoice or bill-based financing.
Before selecting a provider, compare the following factors:
Discount rates and processing fees
Eligibility criteria for businesses and buyers
Minimum and maximum financing amounts
Application requirements and processing timelines
Repayment arrangements and recourse conditions
Choosing a suitable provider can help the business balance the need for timely funding against the total cost of financing.
Step 4: Prepare the Required Documents
Documentation requirements differ among providers. MSMEs may be asked to submit:
Business registration documents
PAN and applicable GST registration details
KYC documents of the business and authorised signatories
Outstanding invoices or bills
Purchase orders and proof of delivery, where applicable
Buyer acceptance or payment confirmation
Bank statements and financial records
Providing accurate and complete documents can reduce verification delays and improve the efficiency of the application process.
Step 5: Submit the Application
After selecting a financing provider and preparing the documents, the MSME submits its application through the provider's designated process.
The application generally includes information about the business, buyer, invoice value, payment due date, and requested financing amount. The provider may request additional details before proceeding with the assessment.
Step 6: Complete Verification and Credit Assessment
The financing provider reviews the application to assess the transaction's authenticity and associated risks. Depending on the financing product, the assessment may consider the buyer's creditworthiness, the supplier's financial position, invoice validity, payment history, and supporting documentation.
Approval is not guaranteed. Applications may be declined or require further information if the invoice cannot be verified or the parties do not meet the provider's eligibility requirements.
Step 7: Review Discount Charges and Financing Terms
Once the application has been assessed, the provider communicates the proposed financing amount and applicable charges.
MSMEs should carefully review the net amount they will receive, the financing period, processing fees, taxes, and any other contractual costs. They should also understand whether the arrangement is with recourse or without recourse.
In a with-recourse arrangement, the supplier may remain liable if the buyer fails to pay. In a without-recourse arrangement, responsibility for certain buyer-default risks may be transferred to the financing provider, subject to the agreement's exclusions and conditions.
Step 8: Receive the Funds
After approval and completion of the required formalities, the provider releases the agreed advance to the MSME.
The business can use the funds to purchase raw materials, replenish inventory, pay suppliers, cover salaries, meet operating expenses, or fulfil new orders.
MSMEs should allocate the funds according to their working capital priorities to ensure that the financing addresses the original cash flow requirement.
Step 9: Settle the Invoice at Maturity
On the invoice's due date, the outstanding amount is settled according to the agreed arrangement. Depending on the financing structure, the buyer may pay the financing provider directly or settlement may occur through another specified process.
MSMEs should monitor payment status and maintain clear records of the transaction. They must also understand their responsibilities if the buyer delays payment, disputes the invoice, or fails to pay.
Benefits of Bill Discounting for MSMEs
Improved Working Capital
Bill discounting can help MSMEs access funds before customer invoices mature, reducing the time money remains tied up in receivables.
Better Supplier Management
Earlier access to funds can help businesses make timely supplier payments and maintain dependable commercial relationships.
Support for Business Expansion
With improved access to working capital, eligible MSMEs may be better positioned to fulfil larger orders, purchase additional inventory, and respond to growing customer demand.
Reduced Cash Flow Pressure
Businesses can use invoice-based financing to manage short-term gaps between outgoing expenses and incoming customer payments.
More Flexible Financial Planning
When used carefully, bill discounting can complement other working capital solutions and help businesses plan around different customer payment cycles.
Common Challenges MSMEs Should Consider
Although bill discounting can be useful, MSMEs should evaluate potential challenges before applying.
Financing costs: Discount charges and fees reduce the amount received against the invoice and can affect profit margins.
Invoice disputes: Incorrect invoices, missing delivery documents, or disagreements with buyers can delay approval or settlement.
Buyer credit risk: The buyer's financial position and payment history may influence approval and financing terms.
Eligibility requirements: Some providers may have minimum invoice values, buyer restrictions, or specific documentation requirements.
Contractual liability: The supplier may remain responsible for repayment in certain circumstances, particularly under with-recourse arrangements.
Understanding these risks helps businesses determine whether bill discounting is appropriate for their circumstances.
Tips for MSMEs to Use Bill Discounting Effectively
Maintain accurate invoices and up-to-date accounts receivable records.
Verify invoice details and payment terms before applying.
Compare multiple financing offers where possible.
Calculate the total financing cost before accepting an offer.
Check the buyer's payment history and creditworthiness.
Review contractual obligations and default conditions carefully.
Use the funds for planned working capital requirements.
Monitor outstanding invoices and follow up on payments promptly.
These practices can help MSMEs make better financing decisions and maintain stronger financial controls.
Conclusion
The bill discounting process provides MSMEs with a structured way to seek early funding against eligible unpaid bills or invoices. From identifying outstanding receivables and preparing documentation to completing verification and receiving funds, each step helps businesses assess and manage their short-term financing needs.
By comparing providers, understanding the total cost, and reviewing payment responsibilities, MSMEs can determine whether bill discounting suits their working capital requirements. When used responsibly, it can help reduce cash flow pressure, support daily operations, and create opportunities for sustainable business growth.