
In today's competitive business environment, maintaining a healthy cash flow is essential for sustainable growth and long-term success. Businesses often face challenges when customers delay payments, even when they have successfully delivered products or services. These outstanding invoices can create cash flow gaps, making it difficult for companies to pay suppliers, manage operating expenses, invest in expansion, and meet financial obligations. Receivables financing offers an effective solution by allowing businesses to access funds tied up in unpaid customer invoices.
Receivables financing is a financial arrangement that enables businesses to use their accounts receivable as a source of funding. Instead of waiting 30, 60, or 90 days for customers to make payments, companies can receive an advance against their outstanding invoices. This approach helps businesses unlock working capital, improve liquidity, and maintain smooth operations without relying entirely on traditional bank loans.
Understanding Receivables Financing
Receivables financing is a type of business financing in which a company obtains funds based on the value of its outstanding invoices. When a business sells products or provides services on credit, it creates accounts receivable. Although these invoices represent future income, the business may need immediate cash to cover its current expenses.
Through receivables financing, companies can convert these unpaid invoices into immediate working capital. A financing provider evaluates the invoices, the creditworthiness of customers, and the overall financial position of the business before providing funding.
Depending on the agreement, businesses may receive a percentage of the invoice value upfront, while the remaining balance is released after the customer pays, minus applicable fees and charges.
This financing method is particularly beneficial for small and medium-sized enterprises (SMEs), manufacturers, wholesalers, distributors, logistics companies, and service providers that regularly offer credit terms to customers.
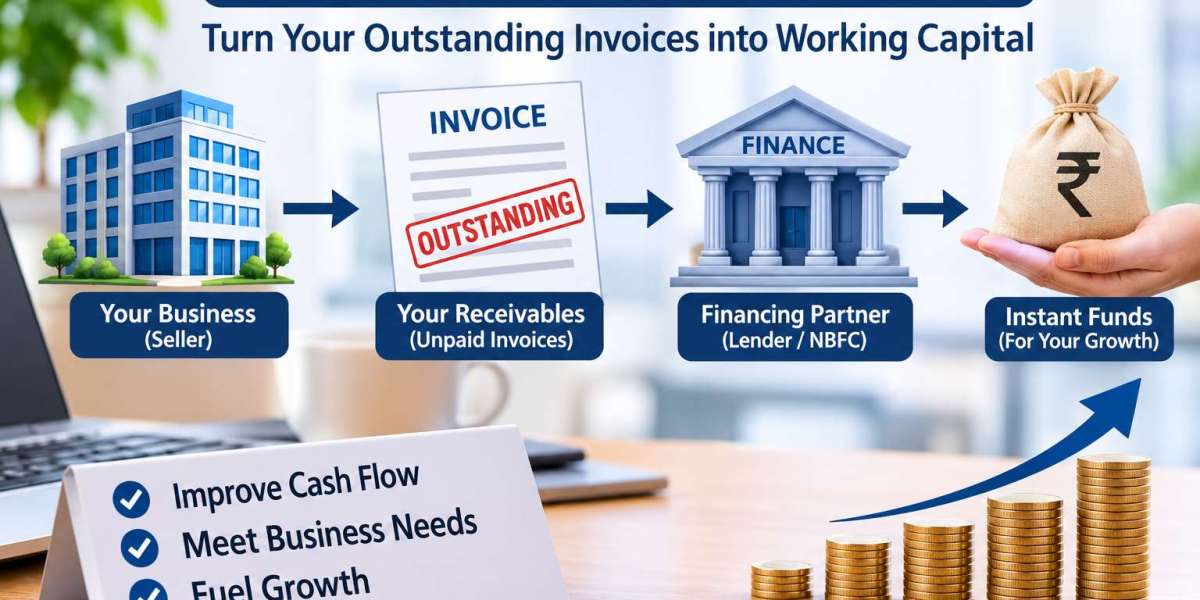
How Receivables Financing Works
The receivables financing process is generally straightforward and designed to provide businesses with faster access to funds.
First, a business delivers products or services to its customers and issues invoices according to the agreed payment terms. These invoices become part of the company's accounts receivable.
Next, the business approaches a receivables financing provider and submits eligible invoices for evaluation. The provider reviews the invoice details, verifies the transactions, and assesses the payment reliability of the customers.
Once approved, the financing provider advances an agreed percentage of the invoice value to the business. The advance rate depends on factors such as customer creditworthiness, invoice quality, industry risk, and the financing arrangement.
When the customer pays the invoice, the outstanding amount is settled according to the agreement. Any remaining balance is released to the business after deducting the financing provider's fees.
For example, if a company has an outstanding invoice worth $100,000 and the financing provider offers an 80% advance rate, the company may receive $80,000 immediately. The remaining amount is settled after the customer makes payment, subject to applicable fees and contractual terms.
This process allows businesses to access money that would otherwise remain tied up in unpaid invoices.
Key Types of Receivables Financing
There are several types of receivables financing solutions available, depending on the financial requirements and business structure.
Invoice Financing: Invoice financing allows businesses to borrow money against outstanding invoices while typically retaining responsibility for collecting payments from customers. It provides flexibility and helps companies manage short-term cash flow requirements.
Invoice Factoring: Invoice factoring involves selling outstanding invoices to a factoring company at a discounted value. The factoring provider generally takes responsibility for collecting payments from customers. This option can reduce administrative work and improve cash flow management.
Accounts Receivable Financing: This arrangement allows businesses to use their accounts receivable portfolio as collateral to secure funding. The financing provider evaluates the value and quality of the receivables before determining the available credit facility.
Selective Invoice Financing: Selective invoice financing allows companies to finance individual invoices instead of their entire accounts receivable portfolio. It is suitable for businesses that need occasional funding for specific projects or expenses.
Each option offers different benefits, costs, and levels of flexibility. Businesses should carefully evaluate their financial needs before selecting a suitable solution.
Benefits of Receivables Financing for Businesses
One of the most significant advantages of receivables financing is improved cash flow. Businesses can access funds without waiting for customers to complete their payment cycles. This immediate liquidity helps companies manage daily operations more effectively.
Another important benefit is working capital optimization. Instead of allowing large amounts of money to remain locked in outstanding invoices, businesses can use the available funds to purchase inventory, pay suppliers, cover payroll, and invest in business development.
Receivables financing can also support business expansion. Growing companies often receive larger orders and experience increased demand for their products or services. However, fulfilling these orders requires additional working capital. Financing against receivables provides access to funds that can support higher production levels and business expansion.
For small and medium-sized businesses, receivables financing can provide an alternative to conventional bank loans. Traditional lending institutions may require extensive documentation, collateral, and lengthy approval processes. Receivables financing focuses significantly on the quality of outstanding invoices and the creditworthiness of customers.
Additionally, certain forms of receivables financing can help businesses reduce administrative responsibilities. Invoice factoring providers may manage payment collection and follow-up activities, allowing companies to focus on their core operations.
Improving Cash Flow and Working Capital Management
Effective working capital management is essential for maintaining financial stability. Businesses need sufficient funds to manage the gap between receiving customer orders, delivering products or services, and collecting payments.
When customers receive extended payment terms, companies may experience a cash flow mismatch. Even profitable businesses can face financial pressure if their receivables collection cycle is too long.
Receivables financing helps address this challenge by converting future customer payments into present-day liquidity. This allows businesses to maintain a more predictable cash flow position.
For example, a manufacturing company may receive a large order from a customer who requires 60-day payment terms. The manufacturer must purchase raw materials, pay employees, and manage production costs before receiving payment. By using receivables financing, the company can access funds against its invoices and continue operating without significant cash flow disruption.
As a result, businesses can maintain stronger supplier relationships, meet financial commitments, and take advantage of new commercial opportunities.
Industries That Benefit from Receivables Financing
Receivables financing is suitable for businesses operating across several industries where credit-based transactions are common.
Manufacturing companies can use receivables financing to fund raw material purchases, production expenses, and equipment requirements.
Wholesale and distribution businesses can access working capital to maintain inventory levels and fulfil customer orders.
Logistics and transportation companies can use invoice financing to cover fuel expenses, vehicle maintenance, employee salaries, and operational costs while waiting for customers to pay.
Construction companies can benefit from financing solutions because project payments are often delayed or linked to specific milestones.
Professional service providers, including consulting firms, marketing agencies, and IT companies, can also use receivables financing to manage operating expenses while waiting for client payments.
These examples demonstrate how receivables financing can support different business models and financial requirements.
Factors to Consider Before Choosing Receivables Financing
Although receivables financing offers several advantages, businesses should carefully review the terms and conditions before entering into an agreement.
The first consideration is the total financing cost. Companies should understand the advance rate, service fees, discount charges, administrative costs, and any additional expenses associated with the facility.
The second factor is customer relationships. Some financing arrangements involve direct communication between the financing provider and customers. Businesses should understand how invoice collection will be managed to avoid potential misunderstandings.
Another important consideration is customer creditworthiness. Financing providers generally prefer invoices issued to reliable customers with a strong payment history. Disputed invoices, overdue accounts, and unclear payment terms may affect eligibility.
Businesses should also evaluate whether the financing arrangement is recourse or non-recourse. Under recourse financing, the business may remain responsible for unpaid invoices. Under non-recourse arrangements, the provider may assume certain credit risks, subject to specific contractual conditions and exclusions.
Finally, companies should compare multiple providers and select a financing solution that aligns with their long-term financial objectives.
The Future of Receivables Financing
Technology is transforming the receivables financing industry. Digital platforms, automated invoice verification, artificial intelligence, and data analytics are making financing processes faster and more efficient.
Modern financing providers increasingly use digital systems to evaluate invoices, assess customer payment histories, monitor outstanding balances, and process funding applications.
These developments are improving accessibility, particularly for small and medium-sized businesses that may struggle to obtain traditional financing.
As businesses continue to prioritize cash flow efficiency and financial flexibility, receivables financing is expected to remain an important part of modern working capital management.
Conclusion
Receivables financing is a valuable financial solution that helps businesses unlock working capital from unpaid customer invoices. By converting outstanding receivables into accessible funds, companies can improve liquidity, manage operational expenses, strengthen supplier relationships, and support business expansion.
Whether through invoice financing, invoice factoring, or accounts receivable financing, businesses can choose solutions that match their financial requirements and operational strategies.
In an increasingly competitive marketplace, maintaining consistent cash flow is essential for sustainable growth. Receivables financing provides businesses with an opportunity to reduce cash flow pressure, improve financial flexibility, and make better use of their existing assets. When implemented strategically, it can become an effective tool for strengthening working capital and achieving long-term business success.